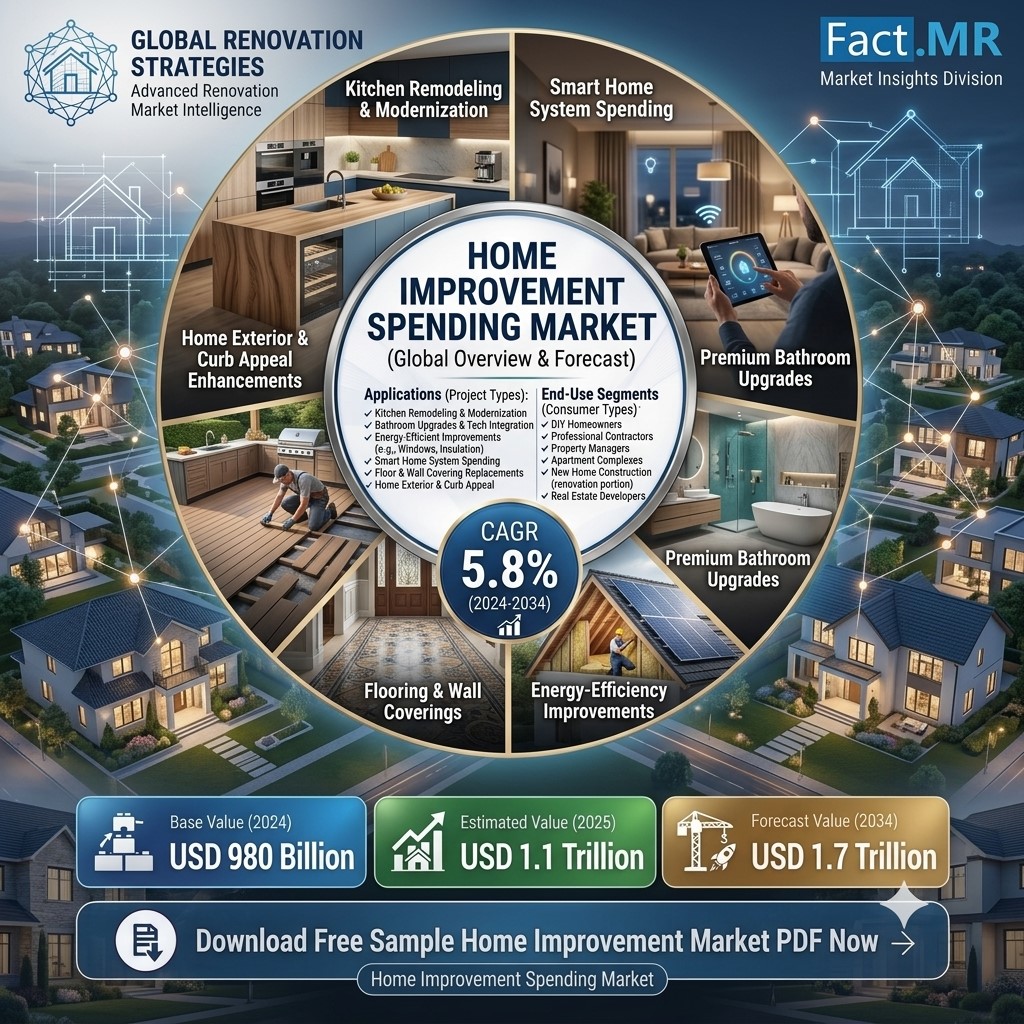
Rockville, MD., September 22, 2026 — The global home improvement market is projected to expand from USD 415.5 billion in 2026 to USD 794.7 billion by 2036, advancing at a 6.7% CAGR during the forecast period. The market reached USD 389.4 billion in 2025, with an absolute opportunity of USD 379.2 billion expected between 2026 and 2036, according to the latest Fact.MR assessment.
Home improvement demand is closely linked to the condition of existing residential properties. Aging roofs, plumbing systems, electrical components, windows, flooring, and interior finishes require recurring repair or replacement. At the same time, homeowners are adding energy-efficient systems and connected technologies as part of broader renovation projects.
Get detailed market forecasts, competitive benchmarking, and pricing trends
Aging Homes and Energy Upgrades Drive Spending
Existing-home repair and renovation cycles remain a central demand driver. The American Housing Survey tracks major improvements and replacements across roofing, flooring, windows, plumbing, wiring, and heating equipment. These recurring needs create a sustained project base for material suppliers, retailers, contractors, and renovation service providers.
Energy efficiency is adding another layer of demand. The revised EU Energy Performance of Buildings Directive requires national building renovation plans, increasing the focus on existing-building upgrades. Insulation, windows, heating systems, and connected energy controls are therefore becoming part of renovation decisions.
Homeowners are also continuing to improve properties when housing transactions slow. Harvard Joint Center for Housing Studies projects annual U.S. homeowner improvement and repair spending at about USD 519 billion through mid-2027, although growth is expected to remain modest.
Public financing programs are widening access to renovation activity in several markets. Brazil expanded Reforma Casa Brasil across all 5,571 municipalities, with financing available for construction materials, labor, project design, and technical support. Germany continues to support energy-efficient renovation through KfW programs.
Building Materials Hold the Largest Product Share
Building materials are projected to account for 62.8% of the market by product in 2026. Renovation work requires physical inputs for structural repairs, interior replacement, and exterior improvements.
Cement and concrete products, bricks and blocks, wood and lumber products, paints and coatings, and flooring materials are among the product categories covered by the report.
Residential renovation is expected to represent 55.4% of the market by application in 2026. The segment combines necessary replacement with upgrades to kitchens, bathrooms, interiors, and structural components.
Homeowners remain the largest end-user group, accounting for 48.9% of the market in 2026. Owner-occupiers directly control the timing and budget of many repair, decoration, and modernization projects.
Smart Home Technology Gains a Larger Role
Smart home technology is projected to hold 41.6% of the technology segment in 2026. Renovation provides a practical installation window for connected lighting, security systems, automation, and energy-management controls.
These technologies can be integrated while electrical systems, walls, heating equipment, or interior components are already being modified. Japan has also expanded its housing-market measurement of energy-efficiency equipment, linking renovation activity more closely with building performance.
Ready-to-use construction materials are forecast to account for 68.3% of the formulation segment in 2026. Pre-mixed and pre-finished products can reduce preparation requirements at the installation site and simplify project execution.
Retail stores remain the leading distribution channel, accounting for 52.7% of the market in 2026. Physical stores continue to provide local availability, product comparison, project advice, and pickup or delivery options for homeowners and contractors.
Germany Leads Country Growth
Germany is projected to record the highest CAGR among the countries assessed, at 7.7% from 2026 to 2036. Brazil follows at 7.0%, while the USA, UK, and Japan are forecast to expand at 6.4%, 5.7%, and 5.0%, respectively.
Germany’s growth is supported by energy-efficiency requirements and renovation financing. KfW adjusted federal efficient-building support in July 2026 and continues financing residential renovations that achieve defined efficiency-house standards. The subsidized credit ceiling for residential renovation was also raised to as much as EUR 150,000 per dwelling.
Brazil’s market is benefiting from expanded renovation finance. Reforma Casa Brasil is available across all 5,571 municipalities, with eligible resources covering construction materials, labor, project design, and technical support.
The USA has a large recurring repair and renovation base. The American Housing Survey records improvements across kitchens, bathrooms, roofing, windows, plumbing, wiring, and heating equipment. Harvard’s forecast of about USD 519 billion in annual homeowner improvement and repair spending through mid-2027 supports continued demand while highlighting sensitivity to project costs.
In the UK, private housing repair and maintenance increased 2.9% in the three months to September 2025. The 2026 Warm Homes Plan also provides a policy route for residential upgrades involving insulation, solar PV, batteries, smart controls, and heat pumps.
Japan has an established framework for tracking renovation activity. Its fiscal 2025 Housing Market Trend Survey expanded coverage of energy-efficiency equipment and renovation tax use.
Project Costs and Labor Availability Remain Challenges
The market faces pressure from project costs and labor expenses, which represent a key short-term restraint. Financing pressure and housing turnover can also cause households to delay or phase renovation projects.
The report identifies skilled-trade availability as another constraint, particularly in developed markets. Material price volatility can further affect project budgets and purchasing decisions.
At the same time, opportunities are emerging around energy-retrofit packages, smart-home modernization, ready-to-use material systems, and local project delivery. Contractors can also use phased projects to separate essential repairs from discretionary upgrades when households face financing pressure.
Competitive Landscape
The competitive landscape includes The Home Depot, Inc.; The Sherwin-Williams Company; DuPont de Nemours, Inc.; Watsco, Inc.; ABC Supply Co., Inc.; Henkel Corporation; Andersen Corporation; Lutron Electronics Co., Inc.; Builders FirstSource, Inc.; and Masco Corporation.
Competition spans building-material manufacturing, contractor-focused distribution, retail, and residential systems. Supplier selection depends on product availability, compatibility with contractor workflows, installation support, and project fulfillment.
The Home Depot serves homeowner and professional project demand through a broad retail network. Its fiscal 2025 annual report listed 2,359 retail stores as of February 1, 2026, alongside more than 1,250 locations within its SRS businesses.
According to Shambhu Nath Jha, Principal Consultant at Fact.MR, “Home improvement demand through 2036 will be shaped by the economics of improving existing homes and by the need to keep aging properties functional. Buyers are prioritizing projects that solve repair needs while improving energy performance or daily usability.”
Top Reports:
Implantable Medical Devices Market
Hospital Acquired Infections Therapeutics Market
Report Scope
The study covers products, materials, and improvement services used to repair, renovate, modernize, or upgrade existing residential properties. It analyzes the market by Product, Application, End Use, Technology, Formulation, and Distribution Channel.
Product coverage includes building materials, wood and lumber products, paints and coatings, and flooring materials. Applications include residential renovation, home repair and maintenance, interior decoration, and exterior improvement.
The report covers North America, Latin America, Europe, East Asia, South Asia and Pacific, and the Middle East and Africa, with country-level analysis for Germany, Brazil, the USA, the UK, and Japan.
The assessment draws on more than 120 sources, over 35 company portfolios, and more than 20 industry interviews across at least 25 countries. The methodology combines existing-housing activity, renovation intensity, material demand, project values, technology adoption, distribution mix, and country-level growth.