Demand for portable oral-care devices, expanding orthodontic treatment and growing consumer investment in preventive dental care are creating opportunities for water flosser manufacturers, according to Fact.MR.
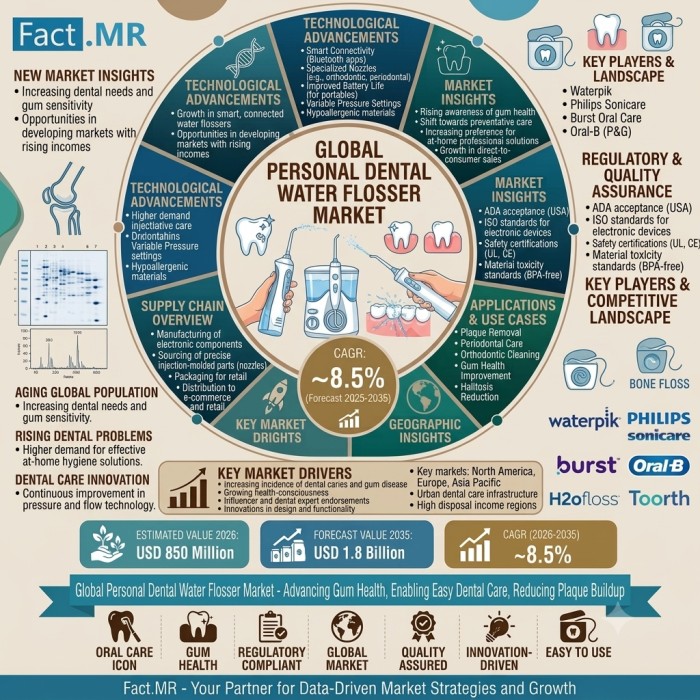
NEWARK, Del., October 13, 2026. The global personal dental water flosser market is projected to increase from USD 278.0 million in 2026 to USD 497.9 million by 2036, registering a compound annual growth rate (CAGR) of 6.0%, according to Fact.MR. The market is expected to generate an incremental opportunity of USD 219.9 million over the forecast period, supported by consumer demand for convenient interdental cleaning, portable appliances and connected oral-care products.
The market was valued at USD 262.3 million in 2025. Fact.MR attributes its projected expansion to growing interest in preventive oral hygiene, professional recommendations for water flossers and increasing demand from consumers undergoing orthodontic treatment or receiving dental implants. Cordless products are gaining attention because they offer portability and rechargeable operation, while smart models are creating opportunities for manufacturers to differentiate their products through connected features.
Get detailed market forecasts, competitive benchmarking, and pricing trends:
Where growth is fastest
India leads the country-level outlook, with Germany and Brazil also expected to record growth above the global market rate. Fact.MR provides the following country forecasts for 2026–2036:
- India: 7.5% CAGR. Rising middle-class spending on oral care, wider organized dental retail and greater awareness of preventive dental hygiene are supporting demand.
- Germany: 6.9% CAGR. Consumer interest in preventive care, dental professional recommendations and established retail distribution support the market.
- Brazil: 6.3% CAGR. Growing middle-class expenditure on oral care and expanding access through organized retail and e-commerce provide opportunities for suppliers.
- United States: 5.7% CAGR. Established consumer awareness, broad retail availability and Waterpik’s brand position underpin demand.
- United Kingdom: 5.1% CAGR. Preventive oral-care awareness, professional recommendations and distribution through pharmacies and online retailers support adoption.
- Japan: 4.5% CAGR. The market is supported by established consumer demand for personal-care appliances and the availability of established oral-care brands.
The geographic outlook points to different commercial priorities. Suppliers entering India and Brazil can assess opportunities in online retail and value-oriented products, while established markets offer opportunities to differentiate products through design, features and brand positioning.
What leads the market
Cordless models and daily oral hygiene applications account for the largest reported segment shares in the 2026 market outlook.
- Cordless water flossers: 46.0% of the product segment. Rechargeable operation and portability support consumer preference for devices that can be used at home or while travelling.
- Daily oral hygiene: 49.0% of the application segment. Routine interdental cleaning represents the principal use case, extending demand beyond consumers purchasing devices for specific dental-care needs.
- Individual users: 62.0% of end-use demand. Household consumers form the largest end-user category, while dental clinics, hospitals and specialty dental centres provide additional channels for product adoption.
For manufacturers, the segment mix favours products that combine ease of use with accessible retail distribution. Cordless models offer a route to reach consumers seeking convenient alternatives to countertop systems, while connected features may help brands establish higher-priced product tiers.
The hurdle: Price competition and consumer awareness
The market’s main constraint is competition from other oral-care devices and lower-priced imports. Electric toothbrushes compete for retail shelf space and marketing expenditure, while manufacturers from China and Southeast Asia put pressure on prices in the entry-level water flosser segment.
Consumer awareness also varies by market. In emerging economies, water flossers can remain a discretionary purchase, with distribution concentrated in major cities and online channels. Manufacturers must therefore balance product differentiation with affordability and invest in distribution that reaches consumers beyond established premium categories.
Fact.MR identifies smart water flossers with app connectivity and AI-assisted monitoring as an opportunity for premium product development. Specialized offerings for consumers with braces, aligners, dental implants and bridges provide another route to reach defined customer groups through dental professionals.
Recent developments
Fact.MR’s published analysis lists the following company developments by year, without specifying individual months:
- 2025 — Waterpik: The report says the company expanded its cordless water flosser portfolio with premium models targeting travel-friendly and professional-grade use cases.
- 2025 — Philips: The report describes continued water flosser product updates associated with its Sonicare oral-care portfolio.
- 2026 — Panasonic: The report identifies further development of rechargeable and portable water flosser offerings.
These developments reflect competition around product portability, feature differentiation and established oral-care brand portfolios. The report does not provide exact announcement dates for these items.
The companies profiled in the report include Waterpik, Panasonic, Philips, Procter and Gamble Professional, Waterpulse, Nicefeel, H2ofloss and Dexta. Other companies identified in its competitive analysis include Oral-B (Braun), Colgate-Palmolive, Xiaomi Corporation, Jetpik, Mornwell, ToiletTree Products and Fairywill.
Unlock 360° insights for strategic decision making and investment planning:
Analyst perspective
The report’s analyst commentary emphasizes the commercial importance of distribution and professional recommendations:
“The personal dental water flosser category sits at an attractive intersection of consumer wellness spending and professional dental recommendation. Growth is not explosive, but it is durable. The commercial economics are dominated by Waterpik’s brand strength, which commands category leadership across North America and significant global share. The commercial lever that matters is retail distribution combined with dental professional endorsement, because consumers often make purchase decisions based on clinician recommendations reinforced through online reviews. Players that combine strong brand equity with expanding product form factors, particularly cordless and smart app-connected models, will continue to capture premium share while mid-range competitors from Asia compete primarily on price.”
The commentary appears in the Fact.MR report under “Analyst Opinion.” The report’s author listing identifies Md Sanaullah, Principal Consultant, while the page also
Explore More Related Studies Published by Fact.MR Research
Rhizoma Gastrodiae Tablets Market
Critical Care Diagnostics Market
Radiation Proctitis Treatment Market
About Fact.MR
Fact.MR is a market research and consulting firm providing syndicated research, customized research, investment research, and market intelligence across a broad range of industries. Its research coverage includes food and beverage, healthcare, pharmaceuticals, biotechnology, consumer products, chemicals and materials, technology, industrial goods, and packaging.
Fact.MR provides market intelligence designed to help organizations understand market dynamics, emerging opportunities, competitive developments, and changing industry requirements.
Media Contact
Fact.MR
Email: sales@factmr.com
Phone: +1 (628) 251-1583
Website: www.factmr.com